1. Watching the spot price instead of the spread
New buyers track the gold price obsessively and then hand over 20% of it in dealer markup without blinking. The spread — the gap between spot and what you actually pay, plus the gap between spot and what you are later paid on a buyback — is the single largest cost in precious-metals investing, and it dwarfs setup, storage and custodial fees combined.
Standard bullion coins and bars typically carry a few percent over spot. If a quote is far above that, you are not buying gold exposure, you are buying a sales commission with some gold attached. Ask for the buy price and the sell price on the same product in the same conversation, and do the arithmetic before you agree to anything.
2. Buying 'exclusive' or 'proof' coins inside a retirement account
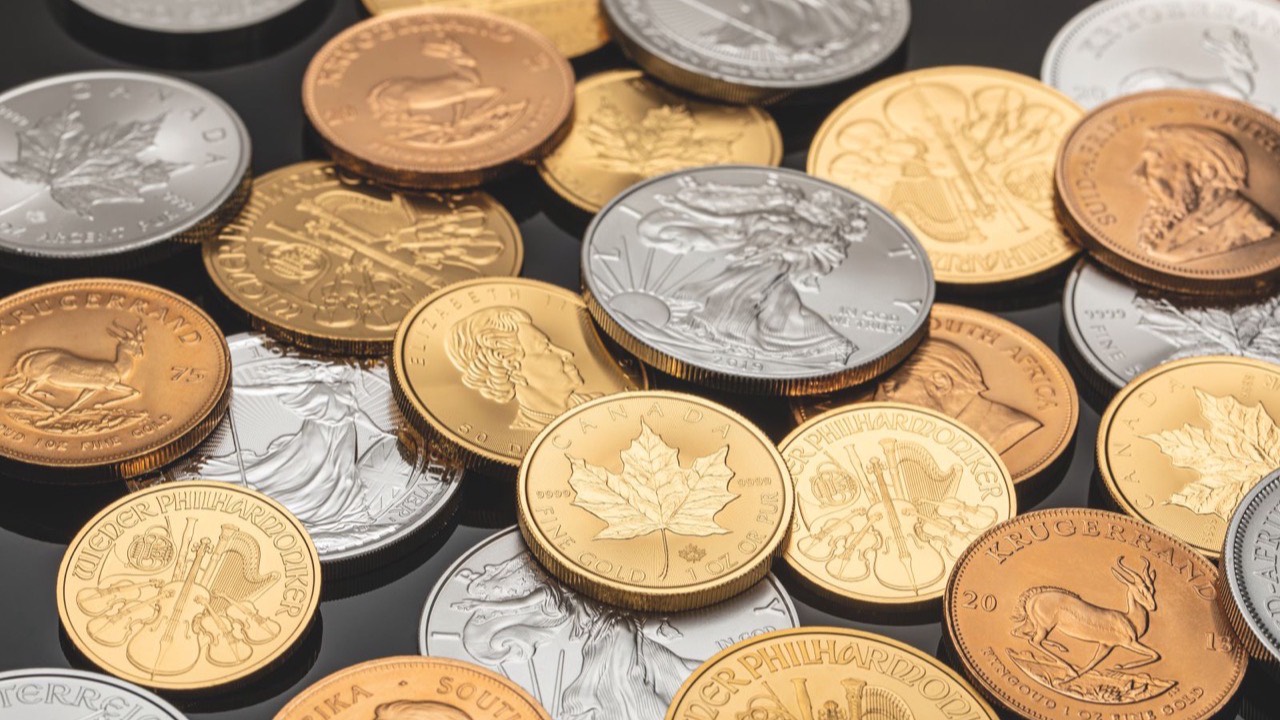
This is the most reliably profitable move in the industry — for the dealer. Semi-numismatic, proof and limited-mintage coins carry markups that can run to several times those on standard bullion, justified by collector scarcity that mostly does not materialise. When you sell, the collector premium evaporates and you are paid roughly the melt value of the metal.
For a retirement account the case is even weaker: an IRA cannot enjoy numismatic upside in any tax-advantaged way that bullion does not also get. If a rep steers you from Eagles or bars toward something with a story attached, that is the moment to slow down and ask what the buyback price would be today.
3. Falling for the 'home storage IRA'
You will find companies suggesting you can form an LLC, have your IRA own it, and keep IRS-approved metals in a safe at home. The IRS position is straightforward: taking personal possession of IRA metals is a distribution. That means the full value becomes taxable income in that year, plus a 10% early-distribution penalty if you are under 59½, and potentially the disqualification of the entire account.
The Tax Court's 2021 decision in McNulty v. Commissioner settled the argument comprehensively, and the taxpayers there lost on every count. IRA metals belong with an IRS-approved depository. Any firm still promoting home storage is telling you something about how it treats compliance generally.
4. Not understanding what storage you are paying for
Segregated storage means your specific coins and bars sit in their own space and the exact items you bought come back to you. Commingled — sometimes called allocated but pooled — means your metal sits with other clients' identical product, and you receive equivalent items of the same type and weight.
Commingled is cheaper and is entirely legitimate. The mistake is paying a segregated price for a commingled arrangement, or assuming segregation when nobody said so. Get it in writing, along with the depository's name, the insurer, and the coverage limit.
5. Letting urgency do your thinking
The sales scripts in this sector run on manufactured scarcity: a mint allocation that expires this week, a fee waiver that ends Friday, a market event that means you must act today. None of it is real. Gold has traded continuously for five thousand years and will be available next week at approximately today's price.
A legitimate provider will send you a written fee schedule, let you take a few days, and still be there when you call back. Judge companies on how they behave when you decline to decide immediately — it is the most informative test available, and it costs nothing to run.
6. Allocating far too much
Gold pays no dividend, retains no earnings and compounds nothing. Its role in a portfolio is to behave differently from everything else when everything else behaves badly. That job is done by a slice, not a majority — most independent guidance lands between 5% and 10%.
The pitch for a much larger allocation usually arrives bundled with a forecast about currency collapse. Treat the forecast and the product recommendation as the single sales proposition they are, and size your position so that being wrong about the forecast does not cost you your retirement.
Ready to compare providers?
See how the leading gold and silver companies score on fees, storage and trust.
This article is editorial content, not investment, tax or legal advice. Rules, rates and limits change — verify current IRS requirements or consult a licensed professional.